
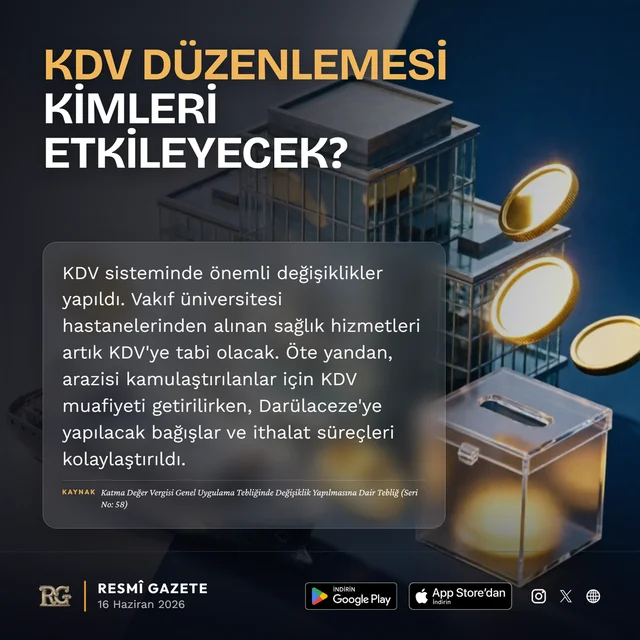
Who Will Be Affected by the VAT Regulation?
Official titleCommuniqué Amending the Value Added Tax General Application Communiqué (Series No: 58)
With the amendment made to the VAT General Application Communiqué; while the services of foundation university hospitals were included in the scope of VAT, the transfer of expropriated immovables was exempted from VAT, facilities were introduced for donations to Darülaceze, and VAT refund processes in imports were simplified.
Before
1) There was a VAT exception for the delivery of properties owned by the Türkiye Diyanet Vakfı (Turkish Religious Affairs Foundation). 2) The services of foundation university hospitals were exempt from VAT. 3) The VAT exception for the transfer of expropriated immovable properties was not clearly defined. 4) The same VAT facilities as associations and foundations were not clear for Darülaceze donations.
After
1) Properties of 'mazbut foundations' (foundations managed by the Directorate General of Foundations) were also included in the scope of exception. 2) As of 1/1/2027, foundation university hospital services will be subject to VAT under general provisions (except for direct operation by the foundation). 3) As of 1/6/2026, the transfer of expropriated immovable properties was exempted from VAT, and the addition of deducted VAT and its expensing were foreseen. 4) Darülaceze (Poorhouse) was included in the exception and donation provisions. 5) For the return of VAT paid over Special Consumption Tax in imports with security, a procedural ease without a tax audit report was introduced.
Details of the Regulation
With this Communiqué, significant updates have been made to the Value Added Tax (VAT) General Application Communiqué. First, in addition to the Türkiye Diyanet Foundation, deliveries regarding premises owned by vested foundations managed by the General Directorate of Foundations have also been included in the scope of exemption. Second, effective from 1 January 2027, deliveries and services of places such as hospitals, clinics, and laboratories operated by higher education institutions (foundation universities) established by tax-exempt foundations will be subject to VAT. However, if these establishments are directly operated by the foundation itself, the exemption will continue. Third, donations and deliveries to be made to Darülaceze have been included in the scope of VAT exemption and facilities provided to associations and foundations. Fourth, effective from 1 June 2026, the transfer of immovables expropriated under the Expropriation Law is exempted from VAT; it has been regulated that the VAT previously deducted for these immovables shall be added back in the tax return and recorded as an expense. Finally, in imports under guarantee, the processing of VAT refunds paid on the Special Consumption Tax (SCT) amount without requiring a tax inspection report has been rendered possible.
Questions You Might Have
- Will I pay VAT if I have surgery at a foundation university hospital?
- Yes, as of 1 January 2027, services at hospitals operated by foundation university higher education institutions will be subject to VAT within the framework of general provisions.
- What will happen to the VAT I previously paid for my expropriated land, will it be forfeited?
- No, the VAT you paid when acquiring the expropriated immovable and claimed as a deduction will be added back in the VAT return and removed from deduction, but it can be deducted as an expense or cost from the Income or Corporate Tax base.
- Is there a VAT advantage on donations made to Darülaceze?
- Yes, with the amendment made, Darülaceze has been equalized with tax-exempt associations and foundations, and granted VAT facilities and exemptions in donations and deliveries.
Key Terms
- Mazbut Vakıf
- Former foundations that no longer have administrators, managed and represented by the General Directorate of Foundations.
- KDV İstisnası
- The non-calculation of Value Added Tax on the delivery of specific goods or services.
- Yüklenilen KDV
- Value Added Tax paid during the stage of production, purchase, or construction of a good or service.
- Kamulaştırma
- The state or public legal entities taking privately owned immovables into public ownership by paying compensation in cases required by public interest.
Affected Sectors
- Healthcare
- Education
- Real estate / construction
- Public sector
- Foreign trade / export
- Civil society / foundations
Where we posted this
Follow Turkish legal developments
REGAS analyzed all 42 items in the Official Gazette of 16 June 2026; we published only 5 of them here.
REGAS summarizes every change in the Turkish Official Gazette in plain language and notifies you.
The REGAS app is currently Turkish-only. If you would like English in the app, the best way to make it happen is to support the developer: get the app and just say so.
REGAS Commentary
This regulation closely concerns real estate owners, foundation university hospitals, and charitable institutions in particular. Taxpayers with expropriated land will no longer calculate VAT, but will be able to lower their tax base by recording the past VAT as an expense. As for the services of hospitals affiliated with foundation universities, since they will be subject to VAT starting from 2027, the costs for those receiving healthcare services from these institutions may increase. Encouraging donations to Darülaceze and reducing bureaucracy in import VAT refunds will act as a lifeline for the market.