
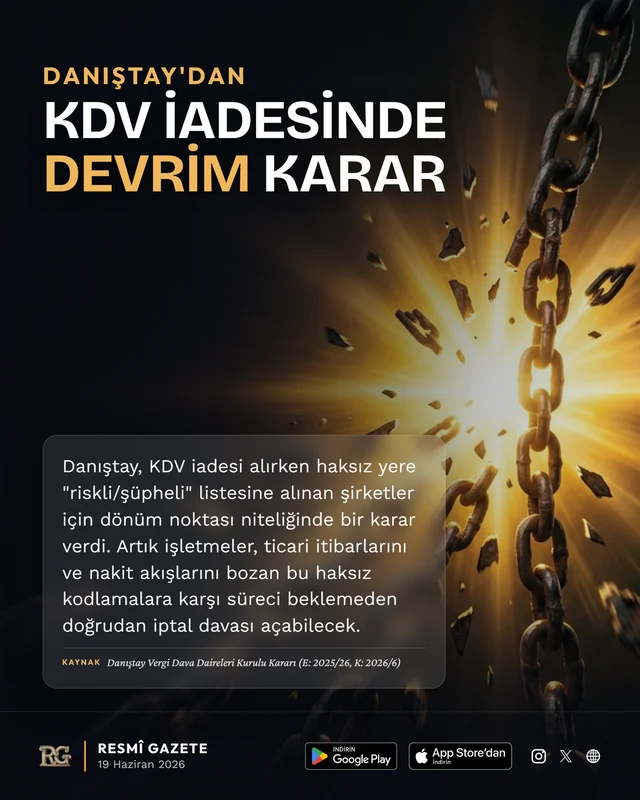
Revolutionary Decision on VAT Refunds from the Council of State
Official titleDecision of the Council of State Plenary Session of Tax Law Chambers (E: 2025/26, K: 2026/6)
The Council of State Plenary Session of Tax Law Chambers ruled that the action of including taxpayers within the scope of "special principles" (taxpayers whose VAT refunds shall be concluded based on a tax audit) pursuant to the VAT Law constitutes a definitive and executable administrative act subject to enforcement, and that in lawsuits filed seeking the annulment of this act, a decision must be rendered by examining the merits of the case.
Details of the Regulation
Gathered to resolve the conflict between the decisions of the Konya and İstanbul Regional Administrative Courts, the Council of State Plenary Session of Tax Law Chambers examined the action of placing taxpayers on the "special principles" list, which stipulates that taxpayers' VAT refund requests be concluded based on a tax audit report. While the Konya Regional Administrative Court argued that this classification was a "preparatory preliminary act" prior to the final decision and could not be directly made the subject of a lawsuit, the İstanbul Regional Administrative Court maintained that the act could be litigated because it directly affected commercial activity and legal interests.
The Council of State emphasized that the tax administration placing a taxpayer in this special category produces direct and adverse consequences on the relevant person's commercial life, reputation, and tax relations. It was stated that this situation could lead to mistrust in the taxpayer's commercial relationships and delay their access to financial resources and the VAT refunds to which they are entitled.
The Plenary Session certified that the act in question is in the nature of a definitive administrative act that is executable and subject to enforcement, ruling that it can be made the direct subject of a lawsuit in the administrative jurisdiction. Consequently, it was concluded that the courts should not dismiss these lawsuits on procedural grounds under the pretext of a preliminary stage, but rather review on the merits whether the factual and legal grounds relied upon by the administration when placing the taxpayer on this list reflect the truth.
Questions You Might Have
- Why can placing a company on the special principles (risky codes) list not be considered merely a 'preliminary stage'?
- Because being added to this list immediately shakes the company's reputation in the market, causes its business partners to distance themselves from it, and by preventing it from receiving the VAT refunds it deserves, can bring its commercial activity to a virtual standstill. These severe consequences render the act directly executable.
- How has the procedural barrier before the tax courts been overcome with this decision?
- Tax courts will no longer be able to procedurally reject taxpayers' lawsuits by stating 'this action is still at the preparatory stage, wait for the lawsuit regarding the final refund rejection'; they will directly review the administration's grounds for listing on the merits.
Key Terms
- Özel Esaslar
- In tax law, the group of risky taxpayers who carry the risk of issuing/using fake or misleading documents and whose VAT refund requests are consequently subjected to a detailed tax audit first, rather than being paid directly.
- Hazırlayıcı İşlem
- Preliminary acts carried out by the administration before making its final decision, such as investigations, report writing, or proposals, which do not produce legal consequences on their own and cannot be made the direct subject of an annulment action.
- Kesin ve İcrai İşlem
- Directly applicable decisions of administrative authorities that create new rights/obligations or alter the existing state within the legal order directly, without requiring the consent of the addressee.
Where we posted this
Follow Turkish legal developments
REGAS analyzed all 43 items in the Official Gazette of 19 June 2026; we published only 3 of them here.
REGAS summarizes every change in the Turkish Official Gazette in plain language and notifies you.
The REGAS app is currently Turkish-only. If you would like English in the app, the best way to make it happen is to support the developer: get the app and just say so.
REGAS Commentary
This decision is a revolutionary shield of protection for all honest businesses placed on the "special principles" (risky/suspicious taxpayer) list based on unfair or insufficient audits. The tax administration's defense claiming "we have not yet performed a final act, we are merely in the audit process" has been invalidated by the judiciary. Companies can now effectively defend themselves against these unfair encodings that tarnish their commercial reputation and block their financial flows by directly filing an annulment action with a request for a stay of execution.