
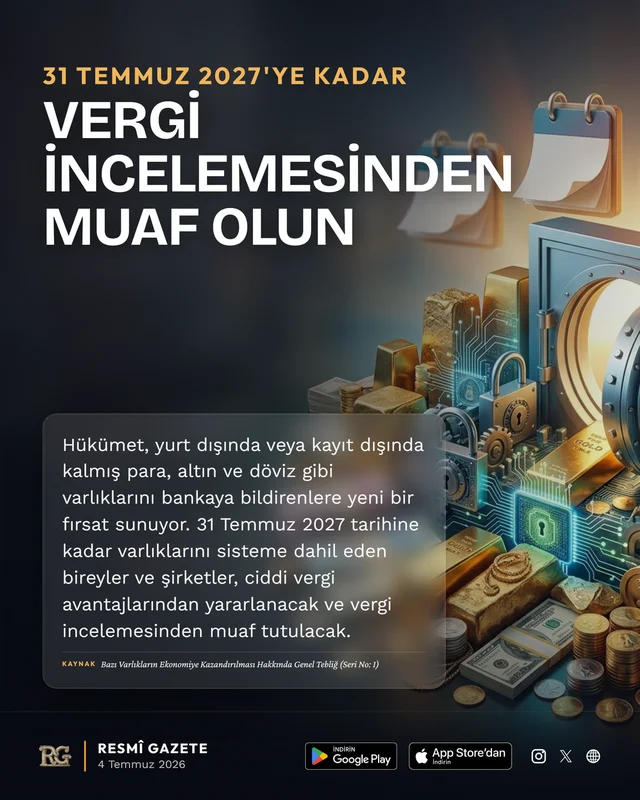
Be Exempt from Tax Audits until 31 July 2027
Official titleGeneral Communiqué on Bringing Certain Assets into the Economy (Series No: 1)
This Communiqué, published by the Ministry of Treasury and Finance, determines the procedures and principles regarding the bringing of unregistered domestic and foreign assets into the economy within the scope of Provisional Article 19 added to the Corporate Tax Law by Law No. 7582. Natural persons and legal entities may benefit from tax advantages and exemption from tax audits by declaring their assets to banks or intermediary institutions until 31 July 2027.
Details of the Regulation
This Communiqué regulates the procedures and principles regarding the implementation of Provisional Article 19 added to the Corporate Tax Law No. 5520 dated 13/6/2006 by Article 10 of Law No. 7582 dated 21/5/2026. The scope includes money, gold, foreign currency, securities, and other capital market instruments belonging to natural persons and legal entities located abroad, as well as assets of the same type that are located in Türkiye but not included in the legal books of account.
Declarations of assets can be made to banks or intermediary institutions from 4/6/2026 until 31/7/2027. The declared assets must be transferred to an existing or newly opened account at banks or intermediary institutions in Türkiye, or physically brought to Türkiye, within two months from the date of declaration. In general, an advance tax of 5% is collected on the declared assets. However, if a commitment is made to hold the assets in time deposit accounts, domestic government debt securities, lease certificates, or venture capital investment funds for specified periods (from 1 year to 5 years), reduced tax rates ranging between 0% and 4% are applied. For declarations made between 1/1/2027 and 31/7/2027, an increase of half a percentage point will be applied to these rates, and in the event of an extension of the period, a total increase of 1 percentage point will be applied to declarations made after 31/7/2027.
Taxpayers are obliged to record the declared assets in their legal books and open a special fund account in the liabilities side of the balance sheet. The amounts and assets in this fund account cannot be withdrawn from the enterprise unless two years have elapsed from the date of declaration, nor can they be used for any purpose other than addition to capital. For those making declarations in compliance with the conditions, no tax audit or tax assessment shall be conducted in relation to the assets subject to declaration. In tax audits initiated for other reasons, if it is determined that the tax base difference arises due to the declared assets, no assessment shall be made up to the declared amount. In case of breach of conditions, the unpaid tax and delay interest shall be collected, but no tax loss penalty shall be applied.
Questions You Might Have
- Can I also declare my real estate abroad within the scope of this communiqué?
- No, you cannot declare it directly. However, you can make a declaration by converting your real estate into assets within the scope of the communiqué (money, gold, foreign currency, securities, etc.) until 31/7/2027.
- What is the period for bringing the assets to Türkiye after making the declaration?
- You must transfer your assets to an existing or newly opened account at banks or intermediary institutions in Türkiye, or physically bring them, within two months from the date the declaration is made.
- How are the tax rates applied to the declared assets determined?
- The general rate is 5%. However, if you commit to holding your assets in specific investment vehicles for a period between 1 and 5 years, the rate decreases to between 0% and 4%. For declarations after 1/1/2027, half a percentage point is added to these rates.
- Will a tax audit be conducted in the future on account of the declared assets?
- Provided that the conditions are complied with, no tax audit or assessment shall be conducted under any circumstances for the amounts corresponding to the declared assets. An audit may be conducted in case of a breach of conditions.
- Can I declare an asset abroad belonging to another company in which I am a partner, in my own name?
- Yes, if the assets, although belonging to natural persons, are disposed of by foreign companies of which they are partners or legal representatives, it is possible to benefit from the provision of the Article provided that they are declared in the name of the relevant natural persons.
Key Terms
- Varlık Barışı
- The practice of bringing unregistered domestic and foreign assets into the economy under certain conditions by recording them in legal books.
- Menkul Kıymet
- Serial documents representing a certain amount, providing partnership or creditor rights, and used as investment instruments (such as stocks and bonds).
- Sermaye Piyasası Araçları
- All other instruments traded in the capital market, such as securities and derivative instruments.
- Rayiç Bedel
- The current market purchase-and-sale value or precedent value of an asset.
- Girişim Sermayesi Yatırım Fonu
- Funds established for the purpose of investing in startup or early-stage companies with high growth potential.
Where we posted this
Follow Turkish legal developments
REGAS analyzed all 43 items in the Official Gazette of 4 July 2026; we published only 4 of them here.
REGAS summarizes every change in the Turkish Official Gazette in plain language and notifies you.
The REGAS app is currently Turkish-only. If you would like English in the app, the best way to make it happen is to support the developer: get the app and just say so.
REGAS Commentary
By offering the current details of the Asset Peace application, this communiqué provides an important incentive for integrating assets into the economy through legal means that had remained unregistered or were held abroad in the past for various reasons. In particular, reduced tax rates and exemption from tax audits open an attractive window of opportunity for potential declarants. While contributing to the reinforcement of both individual savings and corporate capitals on a legal basis, this situation also allows for the shrinking of the informal economy. However, failure to strictly comply with the committed duration and terms of use may give rise to late interest and additional tax liabilities; therefore, a clear understanding of the details is of great importance.