
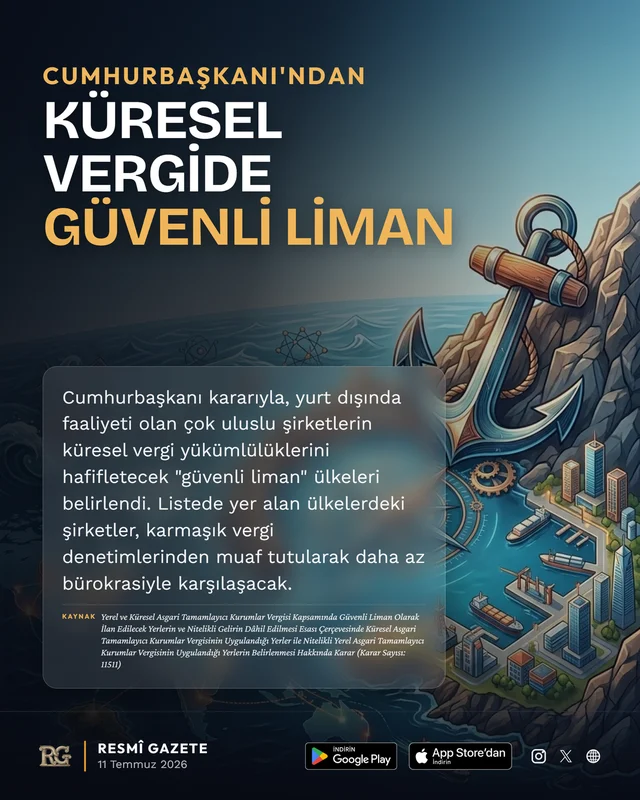
Safe Harbour in Global Tax from the President
Official titleDecision on the Determination of Places Declared as Safe Harbours under the Domestic and Global Minimum Top-Up Corporate Tax, and Places Where Global Minimum Top-Up Corporate Tax is Applied and Places Where Qualified Domestic Minimum Top-Up Corporate Tax is Applied within the Framework of the Qualified Income Inclusion Rule (Decision No: 11511)
With President Decision No. 11511, safe harbours and application areas regarding the 'domestic minimum top-up corporate tax' and 'global minimum top-up corporate tax' practices included in the corporate tax legislation have been determined.
Details of the Regulation
This decision has been prepared based on Corporate Tax Law No. 5520. With the decision, the countries deemed safe harbours for the qualified domestic minimum top-up corporate tax, the places where this tax is applied, and the places where the global minimum top-up corporate tax is applied within the scope of the qualified income inclusion rule have been organized into lists. These determined lists cover a wide geographical area, including Türkiye.
The decision has entered into force to be applied to earnings for accounting periods starting from 1 January 2024. As part of the process of alignment with international tax standards, this regulation aims to ensure the integration of global regulations regarding the taxation of multinational enterprises into domestic legislation.
The implementation of this decision, which will be carried out by the Ministry of Treasury and Finance, directly affects the tax obligations of relevant taxpayers in their international activities and the conveniences provided within the scope of the 'safe harbour'. The countries in the lists are defined as countries that reduce tax compliance costs and provide standardized tax security.
Questions You Might Have
- Does this decision only affect companies within Türkiye?
- No, the decision directly affects multinational companies that are particularly headquartered in Türkiye and operate abroad, or operate in Türkiye, in terms of international tax compliance.
- What is the concrete benefit to a company of being on the safe harbour list?
- Companies operating in the countries included in the list simplify their tax compliance processes by being exempt from the complex calculation and audit obligations provided for in the legislation, or by having these obligations simplified.
Key Terms
- Güvenli Liman
- It is a simplified legal application in tax legislation that assumes transactions or countries meeting certain conditions are at an acceptable tax burden level without entering into complex audit processes.
- Tamamlayıcı Kurumlar Vergisi
- An additional type of tax collected from taxpayers with a low tax burden in order to meet global and domestic minimum tax standards.
Where we posted this
Follow Turkish legal developments
REGAS analyzed all 77 items in the Official Gazette of 11 July 2026; we published only 4 of them here.
REGAS summarizes every change in the Turkish Official Gazette in plain language and notifies you.
The REGAS app is currently Turkish-only. If you would like English in the app, the best way to make it happen is to support the developer: get the app and just say so.
REGAS Commentary
This decision is particularly critical for multinational companies operating cross-border. Companies operating in countries designated as 'safe harbour' will face a more predictable and less bureaucratic burden in their taxation processes. Companies need to update their tax planning and compliance strategies according to these lists.