
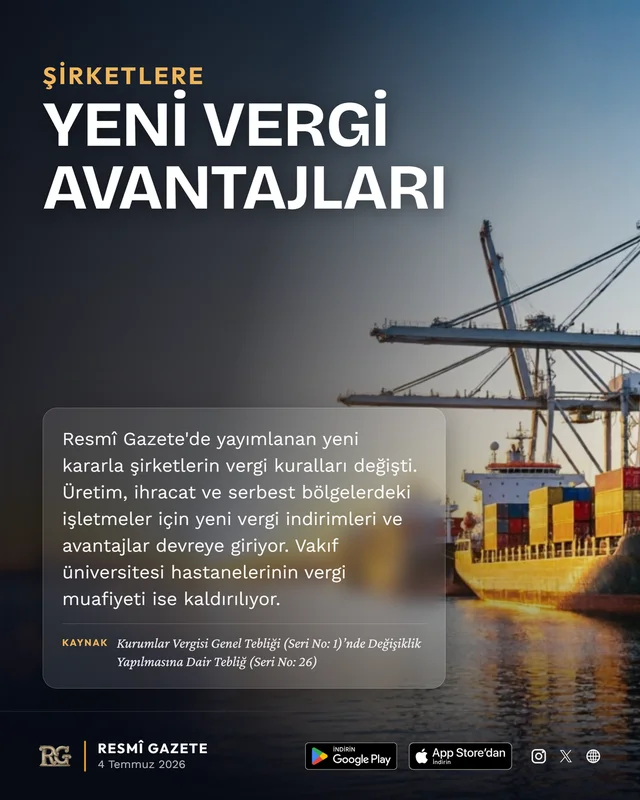
New Tax Advantages for Companies
Official titleCommuniqué Amending the Corporate Tax General Communiqué (Serial No. 1) (Serial No. 26)
This Communiqué, in accordance with Laws No. 7577 and 7582, makes comprehensive amendments to the Corporate Tax General Communiqué (Serial No. 1), terminating the exemption of foundation university health institutions; expanding tax advantages for manufacturing, overseas trade, and qualified service center activities in free zones; and re-determining corporate tax reduction rates and application principles regarding export, manufacturing activities, and initial public offerings.
Details of the Regulation
This Communiqué, published by the Ministry of Treasury and Finance, details the current statutory regulations in the Corporate Tax Law. First, as of 1/1/2027, the corporate tax exemptions of health institutions such as hospitals and medical centers operating within foundation universities will be revoked, and these institutions will be required to establish tax registration. This situation signifies a major change in tax burden within the education and health sectors.
Second, as of 1/1/2026, the tax exemption for companies manufacturing in free zones has been expanded. Now, earnings obtained from the sale of manufactured products not only to abroad, but also into the free zone or to other free zones will be exempt from corporate tax. This amendment aims to encourage trade and integration within free zones. Toll manufacturing activities will also be able to benefit from this exemption under certain conditions (such as industrial registry certificate, assumption of business risk, procurement of raw materials).
Third, reduction rates for earnings obtained from the sale of goods purchased from abroad without bringing them to Türkiye or from brokerage activities for overseas purchase and sale of goods have been clarified. Generally 95%, this reduction rate has been increased to 100% for companies located in the Istanbul Financial Center Zone or in industrial zones deemed appropriate by the President. In this context, overseas sales or brokerage of digital product codes and intangible rights (such as copyright, trademark, patent) will also be eligible for the reduction. However, these earnings must be transferred to Türkiye until the deadline for filing the tax return.
Fourth, similar reductions have been introduced for earnings obtained from abroad by institutions operating as "Qualified service centers." These institutions will be able to deduct 95% (100% for Istanbul Financial Center or designated industrial zones) of the earnings obtained exclusively from these activities from the corporate income. This reduction will be applied for twenty accounting periods, including the accounting period in which the activity commenced. Finally, corporate tax rate reductions applied to manufacturing and export activities, as well as to companies offered to the public for the first time on Borsa Istanbul, have been updated and explained with application examples. Starting from 2027, a reduced rate of 12.5 percentage points for institutions engaged in industrial registry certificate manufacturing and agricultural production, and a reduced rate of 5 percentage points for exporting institutions will apply. Publicly offered companies will benefit from an additional 2 percentage point reduction for five accounting periods.
Questions You Might Have
- What kind of change occurred from a tax perspective for the hospitals of foundation universities?
- As of January 1, 2027, health institutions (hospitals, polyclinics, etc.) of foundation universities will lose their corporate tax exemption and become tax obligors.
- Will a company manufacturing in free zones be able to benefit from the tax advantage even if it sells its products domestically or to another free zone?
- Yes, as of January 1, 2026, earnings obtained from sales of products manufactured in free zones to abroad, into the free zone, or to other free zones will be exempt from corporate tax.
- Does reselling digital product codes (games, licenses, etc.) purchased from abroad to abroad without bringing them to Türkiye provide a tax advantage?
- Yes, corporate tax reduction can be applied for earnings obtained from the sale of digital codes and similar intangible rights sold abroad without being brought to Türkiye and without their nature being altered.
- What reductions have been introduced in corporate tax rates for companies engaged in manufacturing or exporting?
- For 2027 and subsequent years, a 12.5 percentage point reduction (rate 12.5%) will be applied to institutions engaged in industrial registry certificate manufacturing and agricultural production, and a 5 percentage point reduction will be applied to exporting institutions. These reductions do not overlap with each other in certain cases.
- How are the tax liabilities of a company going public on Borsa Istanbul affected?
- With the initial public offering process, companies will benefit from a general 2 percentage point reduction in the corporate tax rate for five accounting periods. This reduction applies prior to other manufacturing and export reductions.
Key Terms
- Kurumlar Vergisi
- A tax levied on corporate earnings.
- Tebliğ
- An administrative regulation that explains the manner of implementation of a legal text or provides clarification on certain matters.
- Muafiyet
- The state of being completely or partially excluded from tax liability or a specific provision of law.
- İstisna
- Specific situations or transactions excluded from the general rule.
- İndirim
- A reduction made from the tax base or tax rate.
- Serbest Bölgeler
- Regions within the political borders of the country where a special regime is applied in terms of customs duties and other tax liabilities regarding commercial and economic activities.
- İstanbul Finans Merkezi (İFM)
- A region with special status aiming to transform Istanbul into a global financial center.
- Nitelikli Hizmet Merkezi
- Centers where foreign investors carry out qualified service activities within the scope of the Foreign Direct Investment Law.
- Fason İmalat
- Outsourcing a part or all of the production stages of a good to another business.
- Sanayi Sicil Belgesi
- An official document issued to industrial enterprises registering their production activities.
- Halka Arz
- Offering a company's shares to the public investors for the first time.
- Ticari Bilanço Karı
- Pre-tax gross profit calculated according to a company's commercial books.
- Matrah
- The amount or quantity on which the tax calculation is made and the tax rate is applied.
- KKEG (Kanunen Kabul Edilmeyen Giderler)
- Expenses that are not accepted as deductible expenses according to tax laws, and therefore cannot be deducted from the tax base.
Where we posted this
Follow Turkish legal developments
REGAS analyzed all 43 items in the Official Gazette of 4 July 2026; we published only 4 of them here.
REGAS summarizes every change in the Turkish Official Gazette in plain language and notifies you.
The REGAS app is currently Turkish-only. If you would like English in the app, the best way to make it happen is to support the developer: get the app and just say so.
REGAS Commentary
This Communiqué contains critical changes, especially for businesses in foreign trade, manufacturing, financial services, and health/education sectors. Expanding tax advantages for companies in free zones and the Istanbul Financial Center may increase the attractiveness of these regions, while the tax burden for foundation university health institutions will increase significantly. Businesses need to update their tax planning and accounting systems considering these new rates and exemptions. Especially complex reduction calculations and overlapping situations of different rates necessitate detailed work with financial advisors. From the perspective of citizens, it should be kept in mind that there may be indirect effects on pricing in foundation university hospitals.